
August 2024 archive. Headlines about a crash, a lack of homes or a mandatory 20% down payment can obscure useful distinctions. The original three graphics are preserved here as historical illustrations. They do not prove that prices cannot decline or that every buyer can find and finance a suitable home.
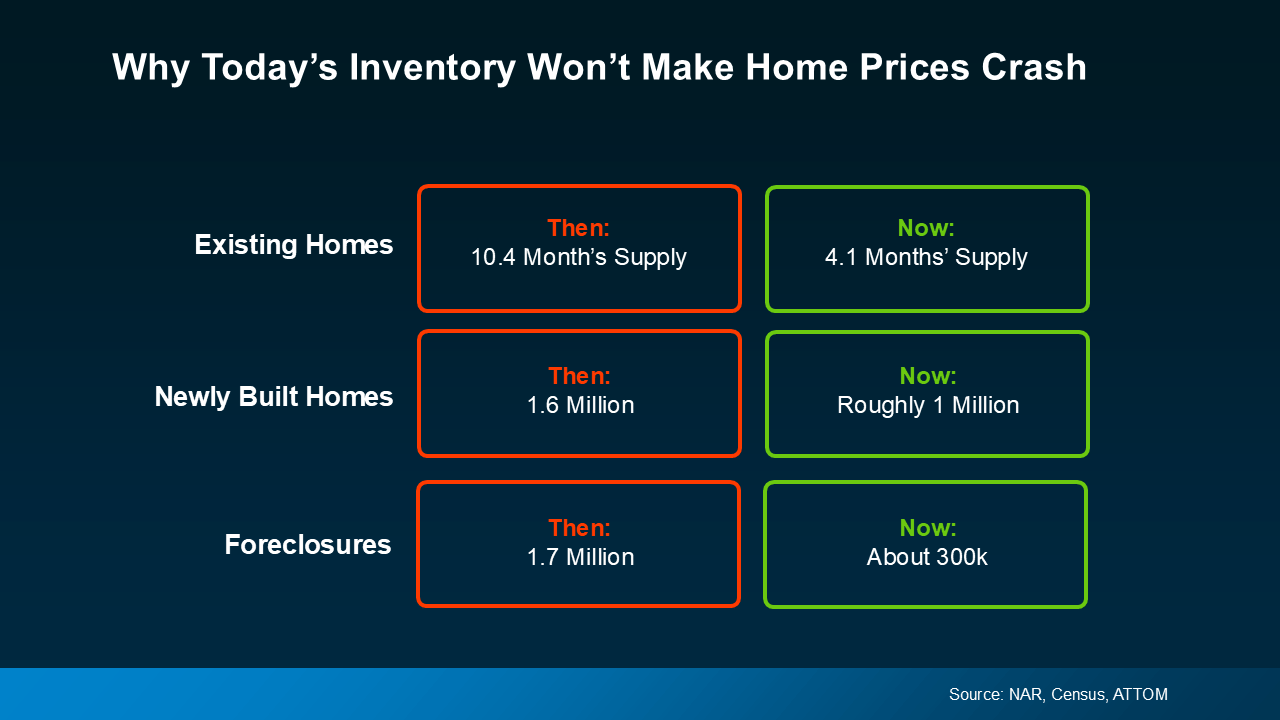
| Measure as labeled | Then | Now |
|---|---|---|
| Existing-home supply | 10.4 months | 4.1 months |
| Newly built homes | 1.6 million | Roughly 1 million |
| Foreclosures | 1.7 million | About 300,000 |
The illustration credits NAR, Census and ATTOM, but does not provide exact dates or definitions for its “Then” and “Now” observations. In particular, it does not establish whether the newly built-home figures count inventory, construction activity or another measure, or whether the foreclosure figures count filings or properties over a specified period. These different indicators must not be treated as a single consistently defined dataset.
Different conditions from the prior crash do not make a future decline impossible. Supply, employment, financing costs, demand and local conditions can change. A national comparison cannot rule out losses on a particular Telluride purchase.
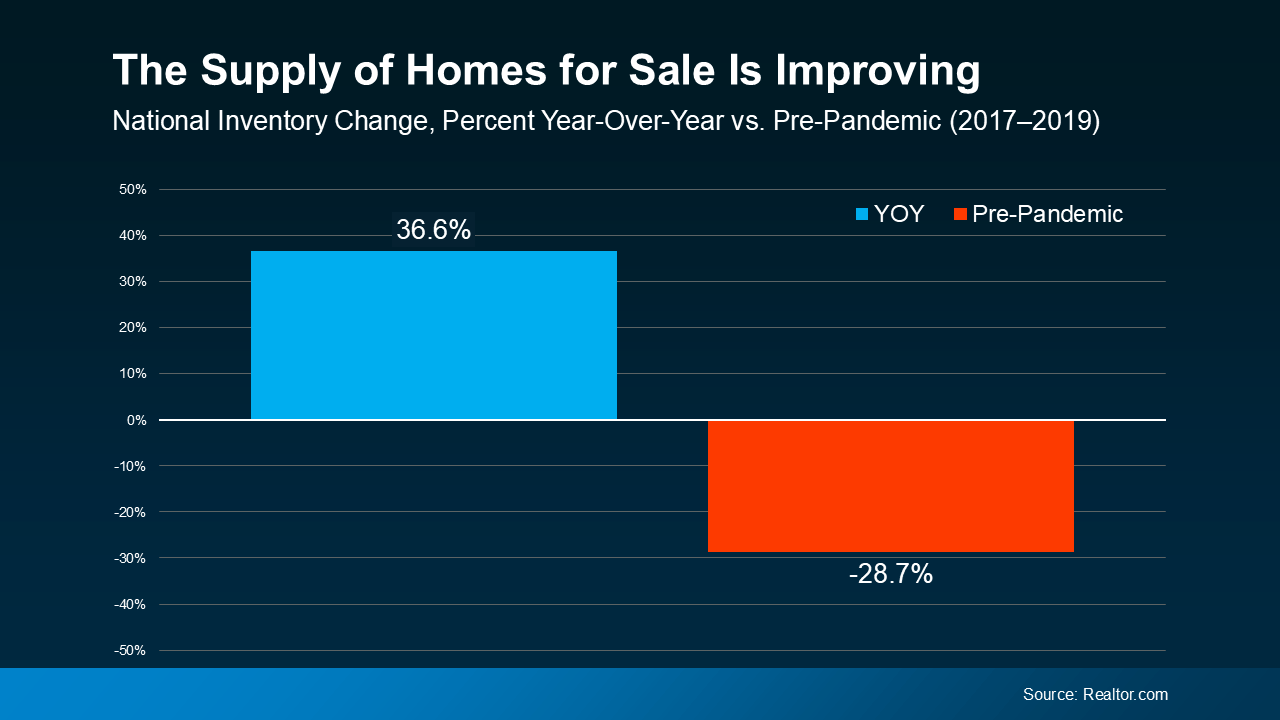
The Realtor.com-attributed graphic reports active inventory 36.6% above the prior year and 28.7% below the 2017–2019 comparison. Both can be true because the baselines differ. The graphic does not identify its observation month. It is retained as an undated historical illustration associated with this archive, not a current inventory count.
More national listings do not mean every buyer has plentiful suitable choices in a particular neighborhood or price range. Check current local inventory, property condition and financing limits before drawing that conclusion.
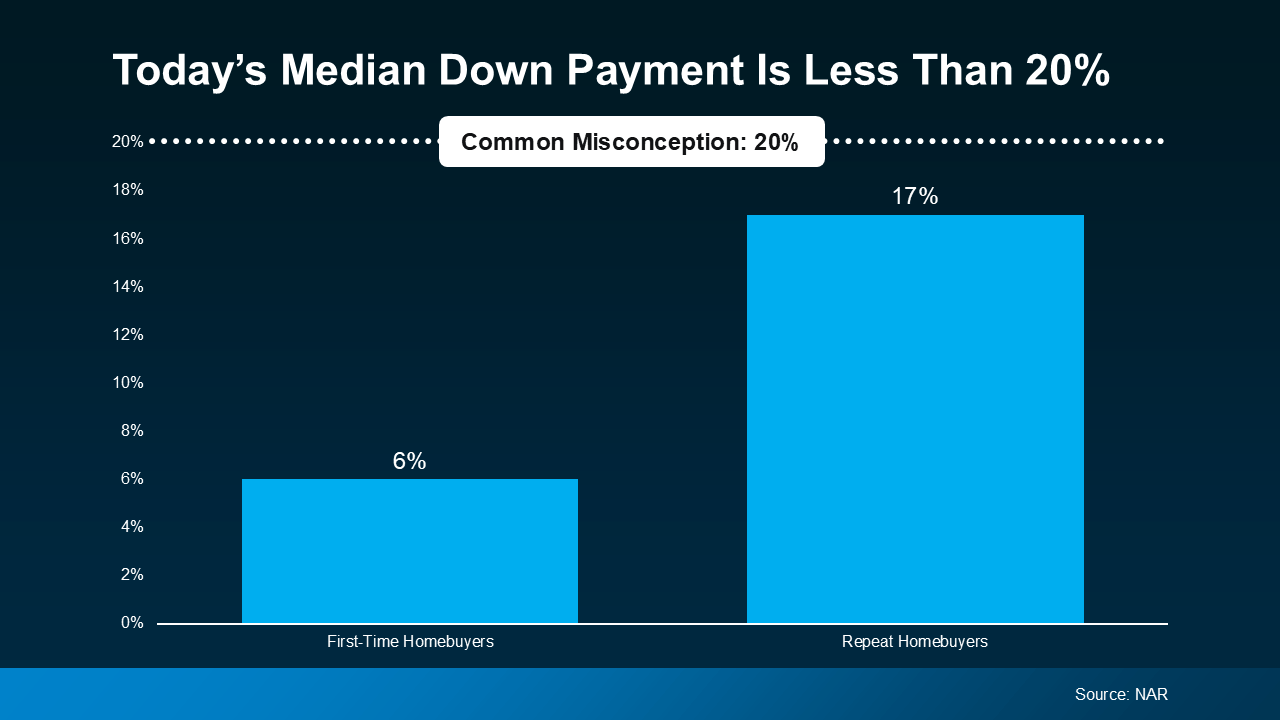
The NAR-attributed illustration gives median down payments of 6% for first-time buyers and 17% for repeat buyers, against a 20% reference line. These figures match NAR’s published 2022 buyer figures. They should not be presented as 2024 requirements or current averages. A median describes surveyed transactions, not the minimum a lender will accept.
Fannie Mae’s mortgage-understanding study, using a 2023 consumer survey, reported that about 90% overstated or did not know the minimum down payment for a typical mortgage. That does not mean 90% specifically believed 20% was required. Repeat buyers may use sale proceeds toward a down payment, but equity is not their only possible funding source.
The CFPB home-loan toolkit describes lower-down-payment options, including FHA programs with 3.5% and zero-down options for qualifying VA and USDA borrowers. Availability depends on the borrower, property, program and lender. A low minimum does not establish approval or affordability.
Discuss the down payment, closing costs, cash reserves, interest rate, mortgage insurance or program fees, and monthly payment with a lender. Also budget for taxes, insurance, maintenance and any HOA costs. A smaller down payment preserves some cash but generally leaves more debt; it is not automatically the cheapest choice. Use current property-level evidence and your own finances to decide whether buying fits your plans.
For comparable sales, competing listings and property-specific questions in Telluride or Mountain Village, contact Anne-Britt Ostlund at Mountain Rose Realty.