
Historical-context note: This article was published in January 2023. The infographic below is preserved as a historical third-party visual and should not be used as current Telluride pricing, lending, tax, or investment guidance.
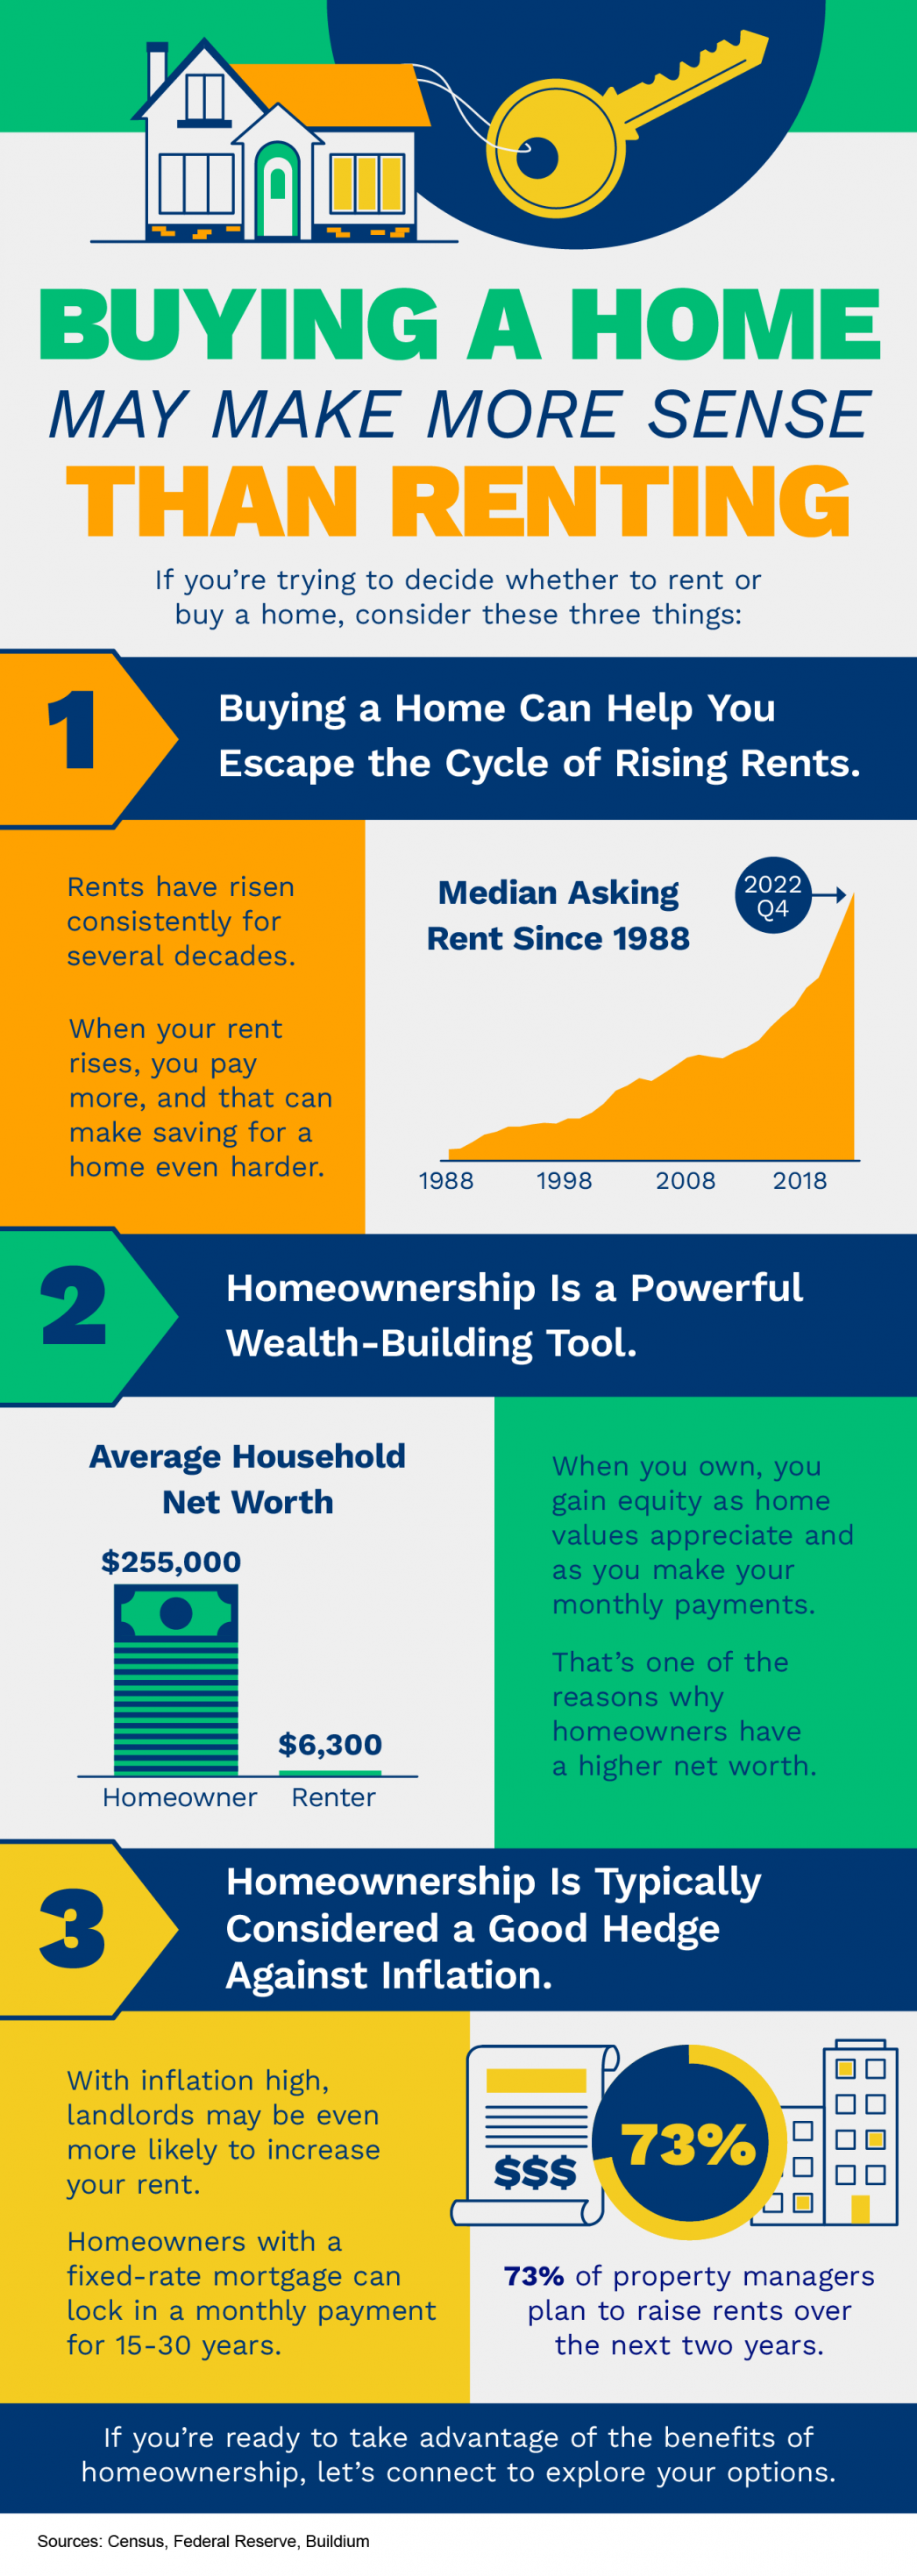
Buying and renting solve different problems. A purchase can make sense for someone who expects to stay long enough to absorb transaction costs and who is comfortable taking responsibility for a particular property. Renting can make sense when flexibility, a shorter time horizon, or lower responsibility for repairs matters more. Neither choice is automatically better, and a local market headline does not determine the right answer for an individual household.
For a purchase, list the expected principal and interest, property taxes, homeowners insurance, mortgage insurance if applicable, HOA or condominium assessments, utilities, routine maintenance, and a reserve for larger repairs. Include cash needed before closing, such as the down payment (including any earnest-money deposit credited at closing), inspections, appraisal, lender charges, title and settlement costs, and any association transfer or document fees. For renting, list rent, renter’s insurance, utilities, parking, deposits, pet costs, and any costs of moving or renewing. Use the actual property and lease terms rather than a broad percentage or a promise about rates.
Consider how long you expect to own or rent, the likelihood of a job, family, health, or lifestyle change, and the costs of selling or ending a lease. A buyer should also consider whether a property’s location, access, maintenance needs, HOA rules, rental restrictions, and ownership structure fit the intended use. A renter should review renewal terms and any limits on use, pets, parking, or subleasing. These questions can matter as much as the initial payment.
The Consumer Financial Protection Bureau provides homebuyer tools for preparing a budget, exploring loan choices, comparing official Loan Estimates, and reviewing closing documents. See the CFPB homebuyer resources before making an offer. Ask more than one qualified lender to explain current loan costs and assumptions. Tax treatment depends on individual circumstances; consult a qualified tax adviser rather than assuming a deduction or benefit. A real estate professional can help identify property records and transaction questions, but cannot determine a buyer’s financing or tax outcome.
Use property search to compare current options, then contact Mountain Rose Realty at ab@mountainroserealty.co or 970-759-4886 to discuss the property-specific costs, access, documents, and restrictions you want to evaluate.