

2023 housing-market context. This article originally discussed two reasons owners were delaying a sale: a favorable existing mortgage and difficulty finding a replacement home. Both deserve a practical comparison. Neither is a reason to assume you must sell now, that prices will rise before you buy, or that refinancing will be available later.
The original discussion contrasted existing mortgage rates below 4% with new 30-year fixed-rate offers around 7%. Those were dated national observations, not today’s quotes or a description of every homeowner. “Rate lock-in” describes an owner’s reluctance to replace a relatively inexpensive loan with more costly borrowing.
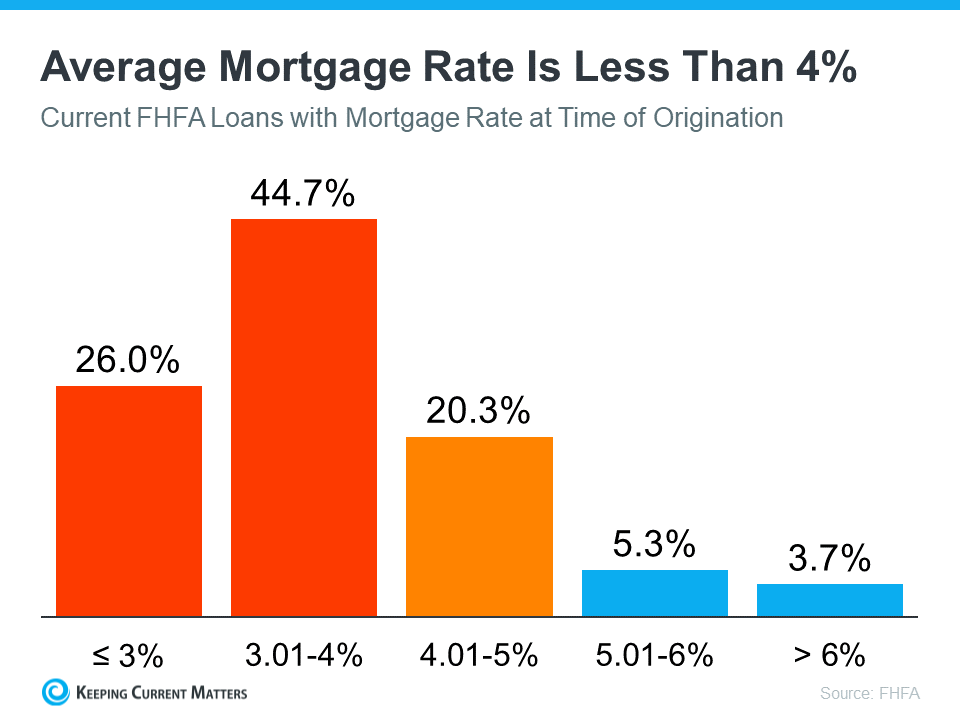
The original FHFA-attributed graphic groups loans by rate at origination: 26.0% at 3% or below, 44.7% at 3.01–4%, 20.3% at 4.01–5%, 5.3% at 5.01–6%, and 3.7% above 6%. Its first two groups total 70.7% at or below 4%. That distribution alone does not calculate the exact average in the graphic’s headline. The reproduced image does not identify its dataset vintage and coverage sufficiently to treat it as a current mortgage-market estimate.
For your decision, compare the amount still owed, remaining term and current payment with a written estimate for the next purchase. A rate on a larger or smaller loan does not tell the whole story. Include down payment, transaction costs, taxes, insurance, association dues, maintenance and a reserve for overlapping housing costs.
Mortgage rates and home prices can move in either direction. A later refinance requires approval and can involve fees, appraisal and loan-to-value requirements. Test whether the purchase works at the financing available when you commit. A possible future improvement is a scenario to compare, not a guarantee that makes an unaffordable payment acceptable.
The original article cited Lawrence Yun’s expectation of tight national inventory over the following months and years. That was an attributed outlook in a 2023 article, not a permanent statement about Telluride supply. Review current choices in the location, property type and price range you would actually buy.
Staying, adapting the current home, or moving can each be reasonable. Anne-Britt Ostlund at Mountain Rose Realty can help compare local property options; a lender can provide the financing estimates needed for the same scenarios.