

February 21, 2023 archive. The two issues discussed here were homeowners’ reluctance to give up a low mortgage rate and concern about finding a replacement home. They can affect listing decisions, but the historical national figures below do not measure current Telluride inventory.
The original article cited First American economist Mark Fleming’s explanation that low existing loan rates and uncertainty about the next home were limiting listings. Here, “lock-in” means the incentive to keep an existing lower-rate loan. It is different from a lender’s rate lock that temporarily fixes a quoted rate for a new borrower.
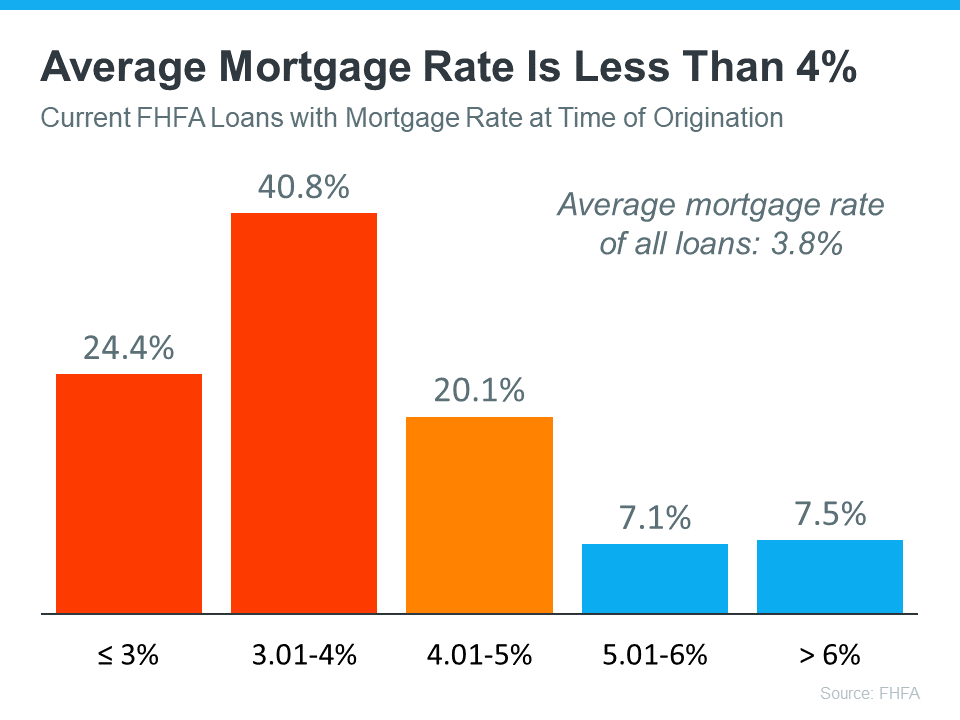
| Rate at origination shown | Share of loans shown |
|---|---|
| 3% or less | 24.4% |
| 3.01%–4% | 40.8% |
| 4.01%–5% | 20.1% |
| 5.01%–6% | 7.1% |
| Above 6% | 7.5% |
The retained FHFA-attributed graphic states an average mortgage rate of 3.8% and describes current loans by their rate at origination. It does not provide a reporting date, detailed loan universe or methodology. The displayed shares total 99.9%, consistent with rounding. It should not be read as a current distribution for every U.S. homeowner, including those without a mortgage.
The February 2023 article compared those existing rates with new mortgage offers above 6% at that time. A new loan’s payment depends on amount, term, rate and other costs. The article’s expectation that rates would fall during 2023 was a forecast, not a guarantee or a current rate quote.
An owner may hesitate to list without a workable replacement plan. Possible options include reviewing available existing homes, newly built homes, temporary housing and sale/purchase timing with the relevant professionals. The original article mentioned builder concessions and mortgage-rate buydowns; availability and terms are specific to the builder, property and loan. A temporary buydown does not make the lower payment permanent.
In its fourth-quarter 2022 report, ATTOM classified 48% of mortgaged U.S. residential properties as equity-rich, meaning estimated secured loan balances were no more than half the estimated property value. This was a national property measure, not the percentage of all homeowners with cash available or a Telluride-specific result.
A seller’s usable proceeds depend on the actual sale price, mortgage payoff, other liens and selling costs. Borrowing against equity creates debt and payments; it does not reduce the purchase price of the next home. Review financing choices with a lender and any tax consequences with a qualified adviser before making commitments.
Low supply alone does not guarantee a seller advantage. A local plan needs current inventory, comparable sales, buyer demand and the owner’s ability to carry or replace the home.
For a review of comparable sales, competing listings and the practical details of a Telluride or Mountain Village property, contact Anne-Britt Ostlund at Mountain Rose Realty.