

August 6, 2024 archive. Home equity is commonly the difference between a property’s current value and the balance owed against it. That calculation is a starting point, not a sale-proceeds estimate, a tax result or a guarantee of what a home will sell for.
For example, a home valued at $400,000 with $200,000 owed against it has $200,000 in gross equity. Actual sale proceeds will also depend on the final sale price and selling expenses.
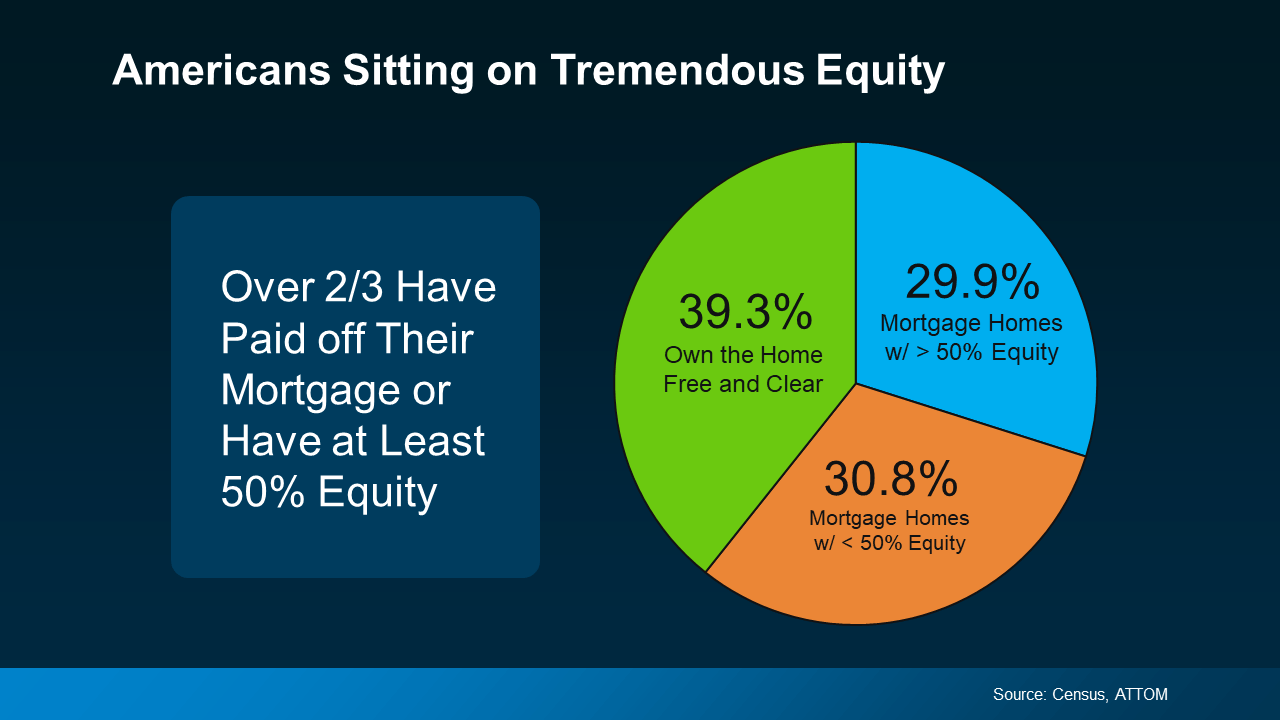
The retained graphic attributes its figures to Census and ATTOM and says more than two-thirds of households shown had either paid off a mortgage or had more than 50% equity. Its displayed categories are 39.3% owning free and clear, a 29.9% slice labeled mortgage homes with more than 50% equity, and a 30.8% slice labeled mortgage homes with less than 50% equity. These are slices of the whole illustration, not percentages each calculated only among mortgaged homes. The graphic does not state its observation date, sampling details or a Telluride-specific breakdown, so it is preserved as a 2024 national illustration rather than a current local measurement.
ATTOM’s Q2 2024 report separately states that 49.2% of mortgaged residential properties were equity-rich, meaning combined estimated loans were no more than half the estimated property value. That denominator and inclusive threshold differ from the pie’s abbreviated labels. The graphic does not document the Census table and vintage needed to reproduce its combined calculation.
The first two displayed groups total 69.2%. That arithmetic describes the categories in the graphic; it does not tell a particular owner’s equity, borrowing capacity, tax position or ability to buy another property.
A current equity review needs a defensible value estimate, current loan payoff information and a list of costs. Sale proceeds can be reduced by commissions, concessions, transfer and closing charges, payoff amounts, repairs, taxes and the cost of the next home. Equity is not the same as cash available at closing.
Before shopping for a mortgage or setting a move budget, the Consumer Financial Protection Bureau’s mortgage-preparation guide recommends reviewing credit, finances and loan documentation. Lenders determine qualification under their own current underwriting standards.
For a local pricing discussion and current comparable sales, contact Mountain Rose Realty. Consult qualified tax, legal and lending advisers for advice outside real-estate market context.