

This article's rate figures describe February 2023. They are not today's mortgage rates or a financing offer. The original question remains useful: if rates rise while you are searching, how should you reassess the cost and timing of a purchase?
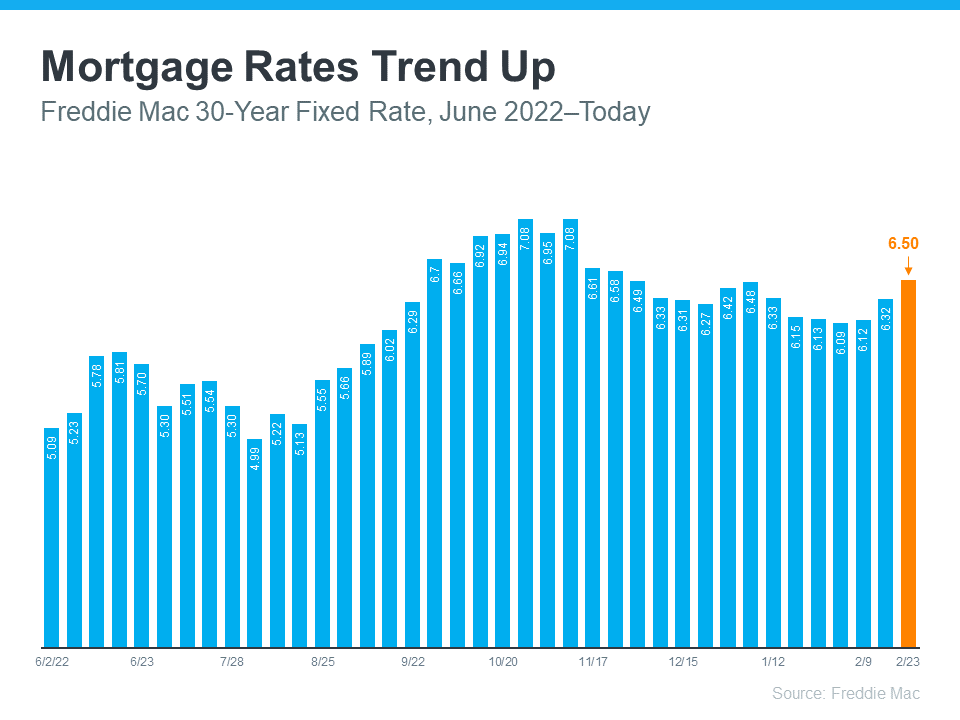
Freddie Mac's February 23, 2023 release reported a 6.50% average for a 30-year fixed-rate mortgage, up from 6.32% the prior week. The original graph runs from June 2022 through February 23, 2023. Its word “Today” refers to that historical endpoint.
A separate MBA release dated February 22, 2023 reported a 13.3% seasonally adjusted decrease in its Market Composite Index for the week ending February 17. That index covers mortgage application volume; it is not a count of Telluride buyers, pending sales or completed home sales. MBA's quoted 30-year rate was 6.62%, from a different survey and week than Freddie Mac's 6.50% figure.
MBA's Joel Kan connected that week's rate rise with expectations about persistent inflation and restrictive monetary policy. That was a contemporaneous explanation, not a formula for predicting the next rate move or proof of a particular property's demand.
A decline in national applications does not establish that your next offer will face less competition. Compare current listings, recent comparable sales, showing feedback where available, price changes and contract activity in the actual property segment. A condominium, in-town home and rural property may have different competition and financing constraints.
Ask a lender to price the loan you can obtain now and explain its rate-lock terms. Review principal and interest together with taxes, insurance, association costs, maintenance and the cash you would retain. Compare purchase prices and down payments under realistic alternatives. If a purchase only works after an assumed refinance or future rate reduction, that assumption deserves explicit reconsideration.
The answer depends on your housing needs, budget, time horizon and available alternatives. Continuing may make sense if the actual costs fit and a suitable property is available; changing the search or waiting may make sense if they do not. Neither rising rates nor a one-week national statistic creates an obligation or guaranteed opportunity to buy.
Contact Anne-Britt Ostlund to review current property choices alongside your lender's financing estimates.