

This April 2023 article asked why prices had not fallen as sharply as some commentators expected. Its supporting graph and economist commentary were national. They do not establish the direction of Telluride prices, explain every homeowner's situation or guarantee that prices cannot decline.
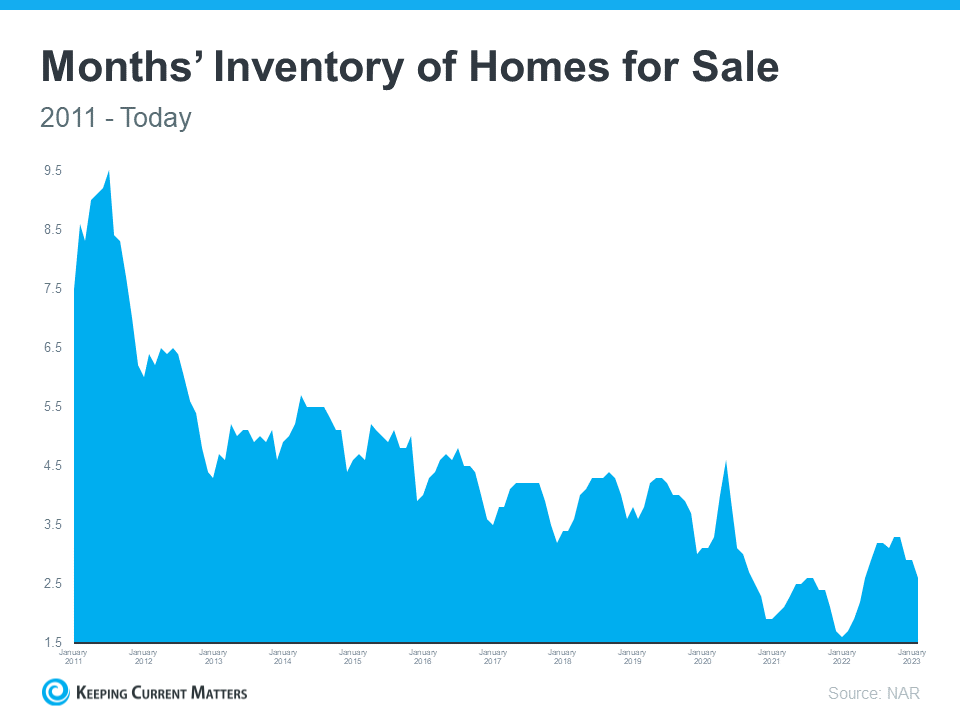
The NAR-labeled graph shows months' inventory from 2011 into early 2023. “Today” is the historical endpoint of the graphic, not the date you read this page. The graph depicts lower supply near the end than in the earlier years, but it does not print individual monthly values or a Telluride series.
Months' supply relates the homes available to the pace at which homes sell. It differs from the number of active listings. Either the supply or the sales pace can change, so a low reading alone does not determine future prices.
The article cited Lawrence Yun's expectation of broadly steady national prices and his view that limited inventory made a repeat of a 30% decline unlikely. It also cited Rick Sharga's expectation that inventory would remain low through 2023. Those were dated opinions, not measured outcomes or guarantees. The original Forbes forecast roundup and Bankrate discussion are references to that coverage; their live pages may have changed since publication.
A supply shortage can support prices when demand is sufficient, but demand, financing costs, household finances, new listings and property condition can also change. Equity and a low existing mortgage rate may reduce some owners' incentive to move; neither describes every owner or rules out distressed sales. The article's earlier statement that supply and demand would not allow a crash was too categorical.
Use a defined geography, property type and period. Compare active listings, new listings, completed sales, price reductions, days on market and relevant comparable properties. Separate median sale-price changes caused by the mix of transactions from evidence about comparable home values. Small luxury-market samples need particular care.
The original claims that a strong job market, new businesses and relocation were causing steady Telluride appreciation did not include a local employment series or transaction analysis. They should not be treated as demonstrated causes or an investment promise.
A buyer can compare current choices with the full cost of ownership and an affordable alternative. A seller can review likely competition, property preparation, pricing evidence and timing. Neither should rely on a national crash prediction, positive or negative, in place of property-specific evidence. Contact Anne-Britt Ostlund to discuss the local comparison relevant to your plans.