
December 2023 archive: This article explains the rate outlook discussed when it was published on December 27, 2023. Its charts and forecasts concern that period. They are not a current mortgage quote or a promise about future rates.
The Federal Reserve raised its policy rate during 2022 and 2023 to restrain inflation. Its federal funds target influences financial conditions, but it does not set the interest rate a lender offers on a home mortgage. Inflation expectations, bond-market yields, mortgage securities and lender pricing also matter.
The original chart shows these meeting-by-meeting increases in basis points, with 100 basis points equal to one percentage point: March 2022, 25; May, 50; June, July, September and November, 75 each; December, 50. In 2023, February, March and May each show 25; June, zero; July, 25; and September, November and December, zero. The zero bars mean no increase at those meetings, not a zero policy rate.
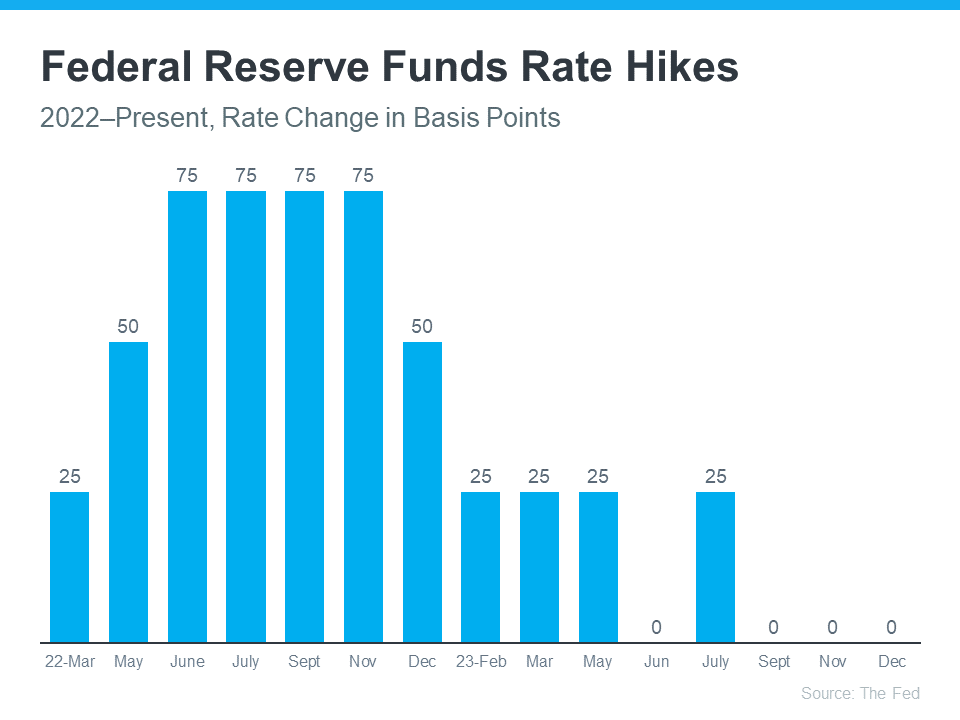
By the final meeting of 2023, inflation had eased and the Fed had held rates unchanged at three consecutive meetings. The original article cited the New York Times discussion of three possible cuts during 2024. The Fed's December 13, 2023 projections show a median year-end federal funds rate of 5.4% for 2023 and 4.6% for 2024, consistent with roughly three quarter-point reductions. Those were participants' conditional projections, not a scheduled commitment or proof that inflation had been solved.
The weekly national series begins in January 2023 and ends on December 14, 2023. It shows the 30-year fixed average peaking at 7.79% on October 26 and later dropping below 7%. The December 14 Freddie Mac release reports 6.95%, down from 7.03% the previous week; the comparable year-earlier rate was 6.31%. The chart's ending value is therefore earlier than this article's December 27 publication date.
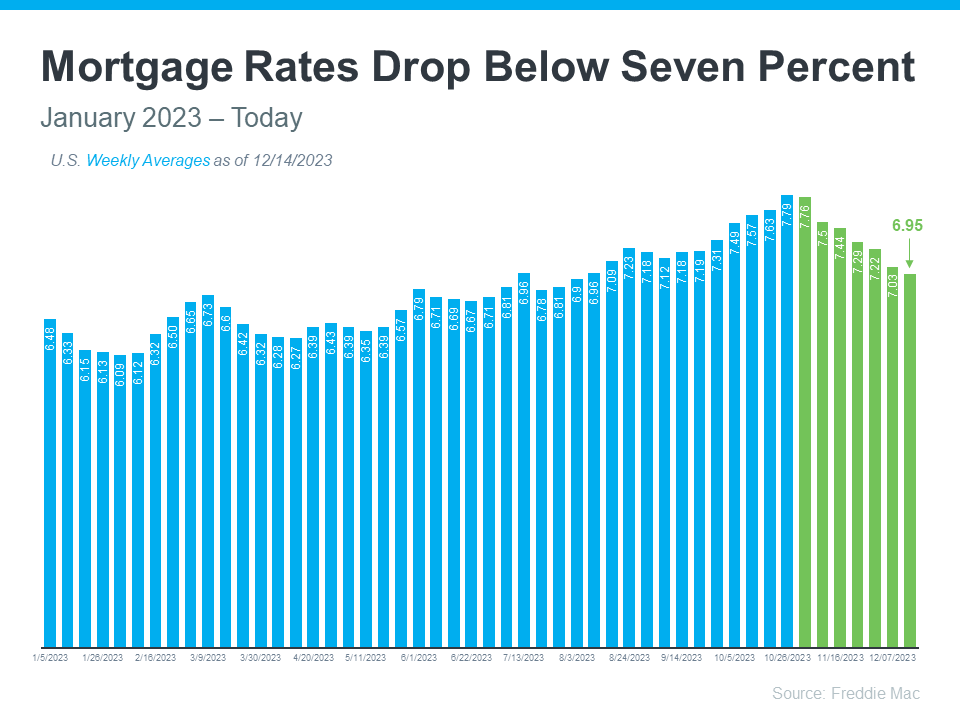
Freddie Mac's survey is a national benchmark for conventional, conforming, fully amortizing purchase loans with 20% down and excellent credit. A Telluride jumbo loan, second-home loan or other borrower profile can carry different pricing. The late-2023 decline made further reductions a possibility, but the pause alone did not establish a continuing downward trend through 2024.
For the same loan amount and term, a lower rate reduces principal-and-interest payments. Total affordability still includes the purchase price, down payment, taxes, insurance, association dues, maintenance and cash reserves. For an owner with a low existing mortgage rate, a smaller gap between that rate and a replacement loan can reduce the financial obstacle to moving. It does not remove selling costs or guarantee that a suitable replacement home will be affordable.
The useful planning step is to compare a written lender quote and current local options with your own budget. A rate forecast should not substitute for a loan approval, a price analysis or a decision about how long the property will fit your needs.
For a Telluride purchase or sale, contact Anne-Britt Ostlund at Mountain Rose Realty to compare local properties and coordinate with your lender.