
December 2023 archive: This planning guide follows the milestones illustrated in the original homebuying graphic. It is a general sequence, not a promise that a particular home, loan, contract term, or move will work for a buyer.
Homebuying decisions usually move through a connected set of tasks: assembling appropriate support, understanding finances, comparing homes, deciding on an offer, completing due diligence, and preparing for closing and move-in. The exact order and requirements vary with the property, contract, lender, title work, association documents, and the buyer’s circumstances.
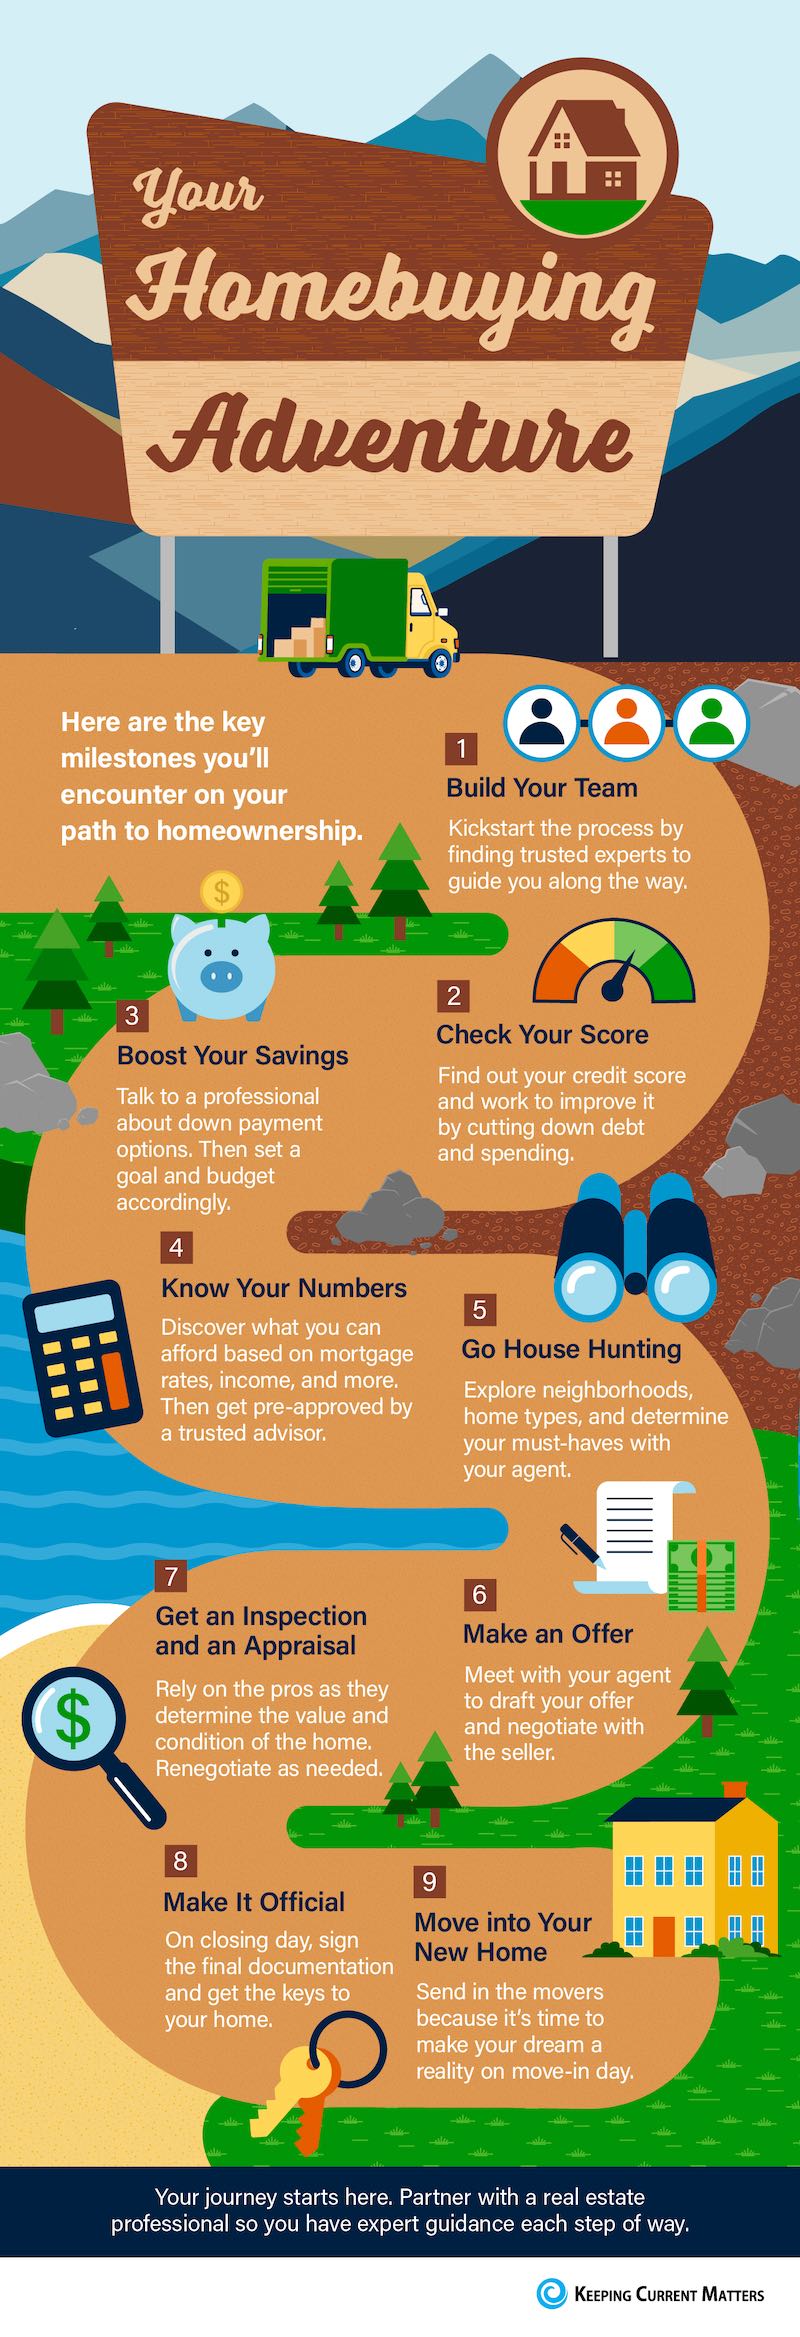
The graphic displays these planning labels: build your team, check your score, boost your savings, know your numbers, go house hunting, get an inspection and an appraisal, make an offer, make it official, and move into your new home. Its visual numbering is not a reliable count of separate legal or lending steps, so use it as a logical planning sequence rather than a fixed ten-step checklist.
A buyer may need a lender, broker, title professional, inspector, insurance professional, contractor, attorney, tax adviser, or other specialist. Ask each professional what work they perform, what it costs, whether there are deadlines, and what decisions remain the buyer’s. A broker can help organize a property search and explain brokerage options, but cannot provide individual legal, tax, insurance, inspection, or lending clearance.
The graphic includes checking your credit score and discussing ways to improve it, as well as talking to a professional about down-payment options and setting a savings goal. Ask a lender or qualified housing counselor which steps fit your circumstances. Review your credit information for errors, plan for the down payment and closing costs, and keep appropriate reserves. Do not assume that paying a particular debt or changing an account will produce a specific score or approval result.
When financing is planned, speak with a lender about the current loan scenario, documentation, cash needed for the transaction, and recurring costs. Compare a specific property’s price with possible loan payment, property taxes, insurance, utilities, maintenance, association dues where applicable, and any planned repairs or furnishing. A lower price does not by itself establish a lower total cost.
Write down the property type, location, access, condition, ownership structure, parking, storage, outdoor space, ski or transit access, and timing that matter most. In the Telluride area, compare the particular address and route in the seasons you expect to use it. An attractive listing or neighborhood description is a starting point for due diligence, not proof that every daily-use need will be met.
An offer can include price, earnest money, financing, inspection, appraisal, title, possession, inclusions, and deadline choices. The buyer decides which terms to propose or accept. An inspection and appraisal serve different purposes: an inspection evaluates observable conditions within its scope, while an appraisal is an opinion of value for its stated purpose. Review reports, disclosures, title materials, association documents, and contract deadlines with the professionals appropriate to the question.
Closing and move-in require current instructions from the lender, title company, contract, and service providers. Confirm transfer dates, keys, utilities, insurance, address changes, and any property-specific access or association requirements. A completed contract does not remove the need to plan the practical details of occupying and maintaining the home.
If you want to discuss a current Telluride-area search and the questions that matter to you, contact Mountain Rose Realty. Review the written brokerage relationship before relying on a broker for a particular role.